

Should Companies Charge Employees Deductibles for Preventable Accidents?
Several questions must be asked and answered prior to adopting a corporate policy of charging deductibles for preventable accidents.
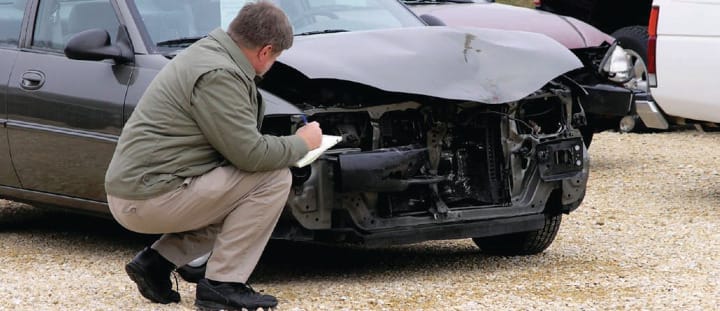
It's the bane of many fleet managers' jobs - the preventable accident. Of course, serious accidents are more than a nuisance. With police reports to file, insurance forms to manage, and repairs to oversee, those minor fender benders and dinged doors can cause significant headaches and paperwork. To instill a sense of responsibility in employees who have the keys to company vehicles, many employers may consider charging workers a deductible after a preventable accident.
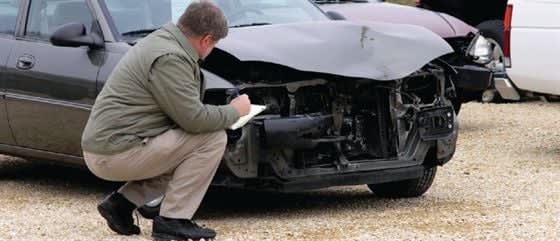
The Federal Motor Carrier Safety Administration (FMCSA) defines a preventable accident as "one which occurs because the driver fails to act in a reasonably expected manner to prevent it." Preventable accidents can occur when drivers are texting, speeding, intoxicated, tired, or simply not paying attention.
However, before instituting a policy about charging deductibles, there are many factors to consider. Do state and local laws prohibit charging a deductible? Does it matter whether the employee is exempt or non-exempt? Does it make a difference if a company self-insures? How will such a policy affect employee recruiting and morale? What happens if employees are allowed access to vehicles for personal use and a family member causes an accident?
Before adopting a corporate policy of charging deductibles for preventable accidents, a fleet manager must understand all the issues to legally protect the company.
[PAGEBREAK]
State and Federal Laws Vary
Company property can be damaged in a variety of ways besides fender benders. Employees can drop and break a brand-new company phone, infect a corporate-issued laptop with a virus while downloading an e-mail, or break the copy machine while vigorously trying to undo a paper jam.
When it comes to damage to any kind of company property, state and federal laws may restrict or prohibit the company's ability to make payroll deductions for loss or damage. Under the federal Fair Labor Standards Act, employers may deduct wages for loss or damage if two conditions are met:
Before money is taken from an employee's paycheck, he or she must sign a written statement agreeing to the deduction.
The deduction does not bring the employee's hourly rate below the minimum wage or violate overtime requirements. This applies to non-exempt employees who qualify for overtime regulations and minimum wage laws.
When it comes to exempt workers who are not subject to minimum wage and overtime requirements, companies cannot deduct wages directly from salaried employees' paychecks as reimbursement for damage to corporate property, according to a 2006 U.S. Department of Labor Opinion Letter.
According to the Opinion Letter, "It would not matter whether an employer implements such a policy by making periodic deductions from employee salaries or by requiring employees make out-of-pocket reimbursements from compensation already received. Either approach would result in employees not receiving their predetermined salaries when due on a 'guaranteed' basis or 'free and clear' and would produce impermissible reductions in compensation because of the quality of the work performed under the terms of the employer's policies..."
Some states also weighed in on the issue of charging employees out of pocket or deducting money from their paychecks for lost or damaged company property. In California, employers may only deduct for cash shortages, breakages, and equipment loss if an employee acted with gross negligence or through a dishonest or willful act.
The issue of wage deductions for damages is complicated and varies so much by state, fleet managers should consult legal counsel before implementing any type of policy that requires paying deductibles for preventable accidents.
[PAGEBREAK]
Consult Experts When Self-Insured
Many fleet operators may have or are considering self-insurance as a way to save money and gain greater control over insurance policies.
When evaluating self-insurance, it's important to understand your policy and how that relates to deductibles. Self-insurance can mean different things, from higher deductibles to completely eliminating comprehensive insurance coverage.
Since policies and laws vary, this is another area in which it is important to consult the experts. Talk with an insurance broker, state regulator, or lawyer before developing a plan for charging deductibles when a company is self-insured.
Will the Policy Hurt Morale?
Charging a deductible for preventable accidents may seem like sound corporate policy. It saves on the bottom line and makes employees accountable for safe and responsible driving habits. However, charging a deductible can cause a backlash. When wage deductions are not allowed, employees most likely will need to pay out of pocket. This may be difficult to enforce, unless the company is willing to consider termination or suing the employee.
Employees may strongly resent paying out of pocket or seeing money come straight out of their paycheck for an accident that happened while they were working.
Knowing they may take a financial hit, an employee may also fail to report minor accidents or be tempted to lie to the police and the company about how an accident occurred. Employees may also insist an accident wasn't their fault and wasn't preventable at all.
In many cases, local law enforcement can help clarify whether an employee was at fault. Many states now use a proportional system that spreads the blame around. For example, if two vehicles collide, one driver may be considered mostly at fault, but the other driver may share a percentage of the fault.
Assigning blame to an aggrieved employee will certainly not create feelings of goodwill.
There are also administrative aspects of charging employees deductibles. If exempt employees are required to pay a deductible, the policy must be sure to have that in writing. Managers and human resources departments must spend time ensuring all paperwork is completed, accurate, and accessible.
With the administrative work involved, it may be more trouble than it is worth for some companies to charge a deductible, particularly for companies with smaller fleets and fewer drivers.
[PAGEBREAK]
Personal Use Can Impact Collection
Companies should also consider how allowing personal use of company vehicles could affect the ability to collect deductibles. For many companies, the easiest approach is to forbid any type of personal use of company vehicles, particularly for any driver other than the employee. However, in some industries and organizations, allowing personal use of a company car represents a significant benefit that can help recruit and retain talent.
If employees are allowed personal use of a company vehicle, policy must clearly outline who can drive that vehicle. Some companies limit use to a spouse only, while others restrict personal use to immediate family. Some allow any licensed driver over a certain age.
Anyone authorized to use the company vehicle must understand the company's regulations, including the policy on deductibles in cases of preventable accidents. It's worth requiring employees, eligible family members, and anyone else who may drive the car to undergo training or at least sign a written form acknowledging they understand their rights and responsibilities.
Charging employees a deductible is complicated enough - getting an employee's spouse or child to pay may be even more difficult. Some insurance companies encourage employers to include a provision in their policies that explicitly states the employee is responsible for the deductible of any insurance claims that result from an accident while that employee's vehicle is driven for a personal reason, regardless of who was actually driving the car at the time of the accident.
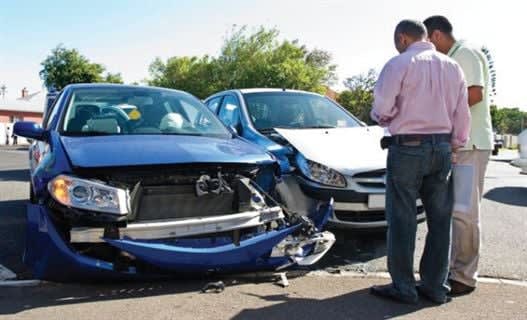
Other Options Available
Rather than charging deductibles, employers may want to consider other approaches to discourage unsafe driving or punish such activities. Education and safe driver training designed to minimize accidents is one proactive approach.
Discipline for accidents is another. As parents of teenagers know, taking away the keys to the car can be a highly effective form of punishment. If an employee has had several accidents, termination may be the final option.
When it comes to charging employees deductibles for accidents they could have prevented, there are many aspects to consider. Whatever approach taken, ensure it makes sense from a financial, logistical, and employee morale perspective. Since laws vary greatly depending on state laws or regulations and type of insurance, seek expert advice from lawyers, insurance brokers, and HR staff familiar with the issues.
Once the right policy has been selected, be sure employees are educated about the policy and have signed all necessary documentation. In case of disputes, the ability to prove a policy was well thought-out and consistently implemented is important.
About the Author
Richard D. Alaniz is senior partner at Alaniz and Schraeder, a national labor and employment firm based in Houston. He can be reached at (281) 833-2200 or ralaniz@alaniz-schraeder.com.
Originally posted on Automotive Fleet
More Safety & Compliance
When Work Trucks Under 26,001 Pounds Need IRP Registration
Think trucks under 26,001 pounds are automatically in the clear when it comes to IRP? Not always. Learn where lighter vehicles can still run into trip permit, apportioned registration, and IFTA compliance requirements when crossing state or provincial lines.
Read More →
Volvo Trucks Releases New Safety Recommendations for Traveling with Pets
One of the most important recommendations for professional drivers traveling with pets is to ensure pets are properly restrained while the truck is moving. Other tips are available in the new guide from Volvo Trucks North America and Center for Pet Safety.
Read More →
API Issues Refueling Safety Guidelines
The American Petroleum Institute offers a list of safe vehicle refueling guidelines, including ways to avoid potential problems with static electricity discharges in fall, winter, and early spring.
Read More →
Winter Fleet Prep: Expert Tips to Keep Vehicles Running Smoothly
Cold weather can expose weak batteries, tires, fuel systems, and maintenance gaps fast. Use this winter fleet checklist to prepare trucks and drivers before temperatures drop.
Read More →
When a Work Truck Breaks Down, the Job Can Stop, Too
A work truck breakdown can stop more than the vehicle. Discover how payloads, jobsites, and specialty equipment change the roadside response.
Read More →
What Stronger Long-Term Fleet Service Partnerships Actually Require
Fleet service partnerships rarely fall apart all at once. Learn the three warning signs that trust is eroding and what fleets and providers can do before downtime, frustration, and lost revenue follow.
Read More →
Applause & TRUCE Software Partner to Improve Driver Safety Through AI-Powered Telematics & Employee Performance Management
Applause has integrated TRUCE driving metrics directly into its employee-first performance and safety platform that transforms mobile devices into AI-powered telematics.
Read More →
How Detroit Assurance with Active Brake Assist Works
Do you want to see what it is like to experience Detroit Assurance’s Active Brake Assist? In this video, Work Truck will put you in the cab to see how it all works and then hear more details from DTNA’s Mike Young.
Read More →
Get Left of Loss: A 5-Step Workplace Violence Prevention Framework for Fleet Operators
Violence risks do not stop at the driver’s door. Learn five practical steps fleets can take to spot threats early and protect workers before loss occurs.
Read More →
How Better Visibility Cut Speeding Violations by 48%
Fleet leaders don't need more data, they need clearer visibility into what the data is saying. This case study explores how one utility replaced speeding-event counts with a single metric — miles driven in violation — to strengthen safety and significantly reduce speeding violations.
Read More →